We’ve known for some time that our financial aid offers can be confusing. For one thing, there is not a lot of consistency from institution to institution, making it hard to compare apples to apples. Another reason is that to make the information streamlined and easy to read, critical information about the components is provided elsewhere and is likely not being read. Finally, our financial aid management systems usually provide the template, and some are easier to customize than others. As far back as 2021, Federal Student Aid (FSA) made recommendations for transparent and consistent formats, but after seeing this College Award Letter Guide in our feed, it seems as a community, we are not quite there yet.
Why are financial aid award letters so important? Students and parents make an enormous investment in higher education; sometimes more than they can afford, even when they understand their financial aid offer. When families make decisions based on unclear or incomplete information in the offer provided to them, at best you risk causing undue stress when it’s time to pay the bill or worse, losing the student entirely if the family didn’t plan for the real expense. A consultant relayed the story of a mother who emailed a competing offer her child received and requested the institution match it. The consultant saw that the other institution listed PLUS in the financial aid offer so that the total ‘aid’ equaled the cost of attendance. Otherwise, the consultant’s institution was offering more gift aid and had lower tuition. They thought the conversation with the mother would be a quick one, but the mother couldn’t get past the higher ‘total financial aid’ number and ultimately the student attended the other school. We don’t know what happened after that, but imagine if the mother didn’t qualify for PLUS? Or if she didn’t really understand it was a loan in her name? Either way it results in a very tough conversation for the financial aid administrator.
FSA has created a college financing template that incorporates all their 2021 recommendations and more. However, it would be extremely difficult to use this format for an aid offer because it has so much information that it would probably add to the confusion rather than reduce it. So, let’s build something somewhere in between this and our current offer template. The goal is to give the students the information they need to calculate how much they will have to pay each semester (based on current eligibility, of course)!
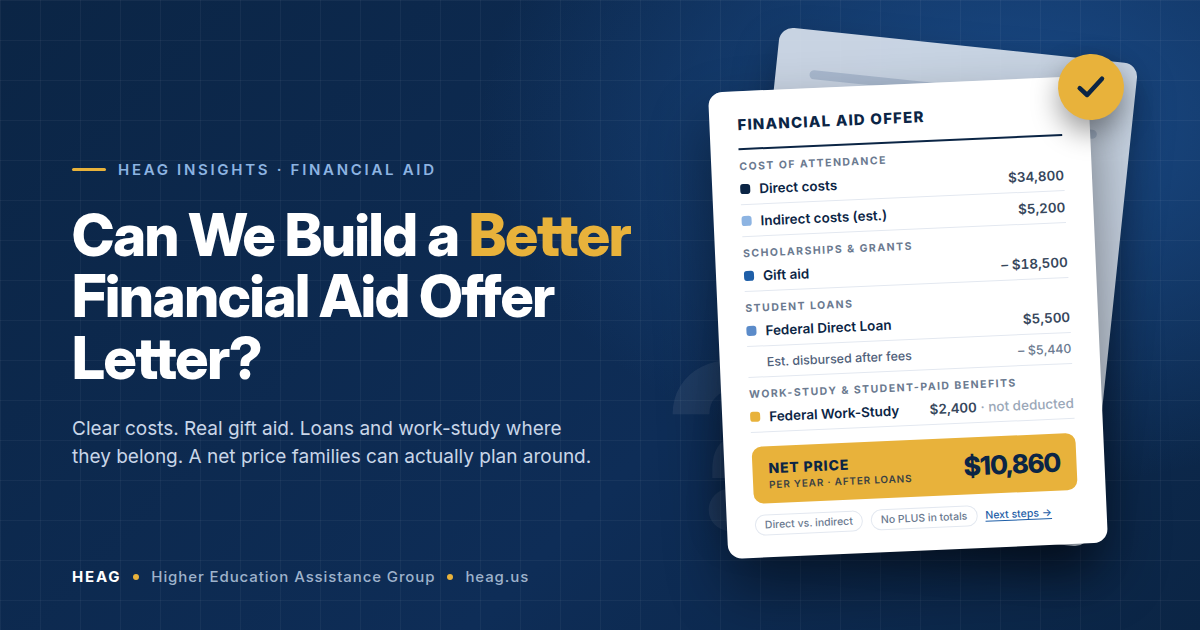
- The Cost: The annual cost of the program should be included in the offer letter but does not have to be broken down into all the increments of the cost of attendance, just direct costs (those billed by the institution) and indirect costs (those incurred as by product of enrollment). If we know the student will live on campus, include room and board in the direct costs, and if not, those expenses should go under the indirect ones. Since the Student Aid Index (SAI) or contribution calculated using institutional methodology doesn’t factor into the cost, it does not provide additional transparency to include that information. In fact, it might cause more confusion.
- Have a separate section for scholarships and grants (they don’t need to be separated from each other, just the other types of financial aid). It is also worthwhile to indicate awards that have different requirements for renewal than most, such as a merit award that requires a higher GPA for renewal compared to an institutional grant. If you can link to that additional information rather than trying to squeeze it into the offer letter, it will be easier to read. Don’t include the names of awards the student is not receiving. For example, if you have a static grants section (Pell, SEOG, State, etc.) and it comes up all zeroes, you’re likely to get a call from the family asking why the student didn’t get any of these. Don’t open that can of worms!
- Some veterans’ benefits are paid directly to the institution and don’t necessarily have to be separated from other ‘gift aid’. They should always be factored into the net price regardless,but there are benefits you need to account for in the total financial aid package that get paid directly to the student. It might be better to put these types of awards in the same section as college work study since its application to net price is entirely dependent on the student’s actions.
- student loans should also be part of the cost calculation, although they should be in separate sections. You can calculate net price both before and after loan disbursements have been applied. The important part is to itemize not just the amount awarded, but also the amount you estimate will be disbursed and what may be deducted from the net price.
- Federal work study is the most difficult award to fit into an offer letter, but it still needs to be included. There are way too many ifs, ands, or buts to include all the pertinent information in the financial aid offer, so make sure to link to information the student can access to estimate earnings and to participate in the program. Ideally, provide the departments on campus that hire work-study students and include links to the application form and other required documents for new hires (like the I-9 and W4). If you can provide or link to information that will help students to estimate taxes to be withheld from their paychecks, it will be even better. Finally, students need to know what to do if they don’t plan to work or work in work-study eligible jobs, so you can repurpose those funds to other eligible students. What you should absolutely include in the offer letter is the statement that work study earnings are not applied directly to tuition or campus housing to explain why it is not deducted from the net price.
- PLUS Loans, private loans, monthly payment plans, and contributions from non-work study employment or savings, should not be part of your financial aid offer letter. These are resources that may be utilized to finance the net price and are not financial aid. Including them with real financial aid awards only confuses people (like the poor mom in our story above). That’s not to say you shouldn’t mention that there are other financing options available in your offer letter, just put the details somewhere else and provide a link to them.
- In every case in which a student must take an action for the funds to be disbursed; you should provide what those steps are but not necessarily in the offer letter itself if it adds a lot of ‘small print’. You likely already have the information on your website and just need to link to it.
- Finally, provide your preferred contact information in your offer letter to ensure students and parents know where to go if they have questions or concerns.
Does your financial aid award letter incorporate all these suggestions? If not, it’s time to consider making changes for the next award year. From compliance review to mastering the financial aid offer templates in your FAMS, our expert consultants are standing by to support you. Email us at info@heag.us and let us know how we can help.
Resources:
- 2026 College Award Letter Guide for Parents
- https://www.ed.gov/media/document/2026-27-college-financing-plan-template-ugrad-112312.pdf
- https://fsapartners.ed.gov/knowledge-center/library/electronic-announcements/2021-10-28/issuing-financial-aid-offers-what-institutions-should-include-and-avoid